

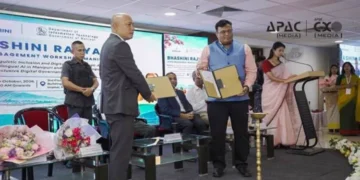



Noida, Oct 5 (APAC Media): Non-banking financial companies (NBFCs) have emerged as a key channel for formal credit in India, accounting for nearly 47% of new-to-credit (NTC) consumer loan originations as of June 2026, according to a joint report by the Finance Industry Development Council (FIDC) and TransUnion CIBIL.
The report, titled Bharat Nirman: NBFC Forming the Foundation of Credit Dispersion, said NBFCs have expanded their credit-active consumer base nearly sevenfold over the past decade, growing about 2.5 times faster than the overall credit industry.
NBFCs accounted for 43% of retail loan originations by volume in June 2026, although their share by value was lower at 30%, reflecting their strong presence in smaller-ticket lending.
Loans of up to Rs 2 lakh accounted for 82% of consumer credit originations, with NBFCs contributing 47% of loans in this segment, compared with 17% for banks. More than 58% of NBFC loans by volume originated in semi-urban and rural (SuRu) markets.
“The NBFC sector has come a long way over the last decade and today plays a much larger role in how credit reaches consumers across India,” said Bhavesh Jain, MD and CEO, TransUnion CIBIL.
He said the sector’s reach was extending beyond first-time borrowers, with a growing presence among credit-experienced customers and across geographies and consumer segments.
The report said the share of semi-urban and rural consumers in the NBFC credit-active base rose from 31% in June 2016 to 59% in June 2026. Women’s share increased from 18% to 27%, while younger consumers accounted for 47% of the base, up from 44%.
NBFCs are also expanding beyond consumer lending. Their share of credit-active commercial entities increased from 10% in June 2021 to 18% in June 2026. NBFC-served entities grew 2.2 times during the period, compared with 1.2 times growth in the overall commercial lending market.
Raman Aggarwal, CEO, FIDC, said the sector was now “far more deeply embedded” in India’s credit system, citing its ability to serve households in smaller towns, first-time borrowers and small businesses.
“As the country’s credit requirements grow, the sector’s ability to combine reach, innovation and responsible lending will remain central to its contribution to the economy,” Aggarwal said.
Portfolio quality has also improved, with the share of above-prime consumers rising from 24% in June 2019 to 32% in June 2026. At the same time, 90-plus days of balance-level delinquency declined from 2.7% to 1.1%.
The report said the next phase of NBFC growth would depend on building more profound customer relationships, expanding product participation and remaining relevant as borrowers’ credit needs evolve.
–ENDS–
Disclaimer: This article is for informational purposes only and is based on publicly available information. APAC Media is not responsible for investment decisions or losses. Please conduct your own research or consult a financial adviser before investing.
Also Read: